How to choose a Kingwood mortgage lender for a reverse mortgage
Key Takeaways
Choosing a reverse mortgage lender is about more than comparing a single rate or estimated loan amount. Take time to understand the terms, ask questions, and check that the loan fits your plans for the home.
- Compare reverse mortgage terms and costs from more than one lender.
- Verify lender credentials and review public complaint resources.
- Complete independent counseling and gather documents early.
- Ask how appraisal, underwriting, and any required repairs could affect timing.
- Understand your payout choices and ongoing obligations before signing.
Understand reverse mortgage options and eligibility
A reverse mortgage lets you draw on home equity without making required monthly mortgage payments, but the balance grows and is repaid later. The right option depends on your age, home, finances, and plans to stay there. Before speaking with a lender, it can help to review Texas reverse mortgage options and note which questions you still have. Treat any estimate as preliminary until a lender and counselor review your situation.
How a HECM differs from a traditional mortgage
With a traditional mortgage, you borrow money and repay it in monthly installments. A Home Equity Conversion Mortgage, or HECM, works differently: you draw on your equity, and repayment is generally due later, such as when you sell the home or move out permanently. You keep ownership of the home, but the loan balance grows over time. A HECM is insured by the FHA; private reverse mortgages have terms that can vary by lender.
A reverse mortgage is not a way to avoid every housing cost or obligation. Compare its structure with other possibilities, such as using savings, selling, or considering a home equity loan, and ask a counselor to help you understand the trade-offs.
How age, home value, and interest rates affect available funds
The amount you may be able to borrow depends on factors that include the youngest borrower’s age, the home’s appraised value, and interest rates. Existing mortgage balances and loan costs also affect how much money may be available to you. As a general matter, older borrowers and higher eligible home values may support a larger loan, but your actual numbers depend on the specific terms. Ask the lender to show how changing assumptions would affect the estimate rather than relying on a single figure.
Who may qualify and which homes may be eligible
HECM eligibility generally includes an age requirement, use of the home as your principal residence, and meeting financial and property standards. The property must also meet applicable requirements, and the lender reviews title and other details as part of the process. Eligibility can depend on your particular circumstances, so ask for a clear explanation of any issue that might affect approval. A counselor can help you assess whether the requirements make sense for your household.
When a reverse mortgage may—or may not—fit your plans
A reverse mortgage may be worth exploring if you want to remain in your home and need access to some of its equity, but it is not automatically the best choice. The loan can become due if you sell, pass away, or move out permanently; falling behind on property taxes or insurance may also create repayment problems. Consider how long you expect to stay, who may inherit the home, and whether you can keep up with its costs. Your long-term plans matter as much as the amount you might receive.
Compare Kingwood mortgage lenders
A Kingwood mortgage lender should be willing to explain the loan in plain language and provide terms you can compare. Look beyond an advertised rate: fees, rate structure, payout choices, and the people handling your file all matter. Use the same questions with each lender so you can make a fair comparison. You can also review Michael Durr’s Kingwood mortgage profile as one source of local mortgage information while doing your own checks.
Verify HUD approval and review lender credentials
For a HECM, check the lender’s HUD approval status using HUD’s resources rather than relying only on a sales conversation. You can also ask whether the lender belongs to the National Reverse Mortgage Lenders Association and what professional standards apply to its members. Request the names and roles of the people you will work with, and confirm how to reach them. These simple checks help you understand who is offering the loan and what oversight or professional commitments may apply.
Check complaint histories through NMLS Consumer Access and the CFPB
Public records can add context to what a lender tells you. NMLS Consumer Access and the Consumer Financial Protection Bureau’s complaint database are free resources you can use to look for licensing information and complaints. A complaint record does not, by itself, explain every side of a dispute, so read what is available and ask the lender about anything that concerns you. Keep a note of your findings alongside the estimates you collect.
Compare loan estimates, fees, and interest-rate terms
Ask each lender for a written estimate and clarify which figures are assumptions, which costs are charged upfront, and whether the rate is fixed or adjustable. Comparing items side by side can reveal differences that are easy to miss in a verbal summary.
| What to compare | Question to ask |
|---|---|
| Interest rate | Is the rate fixed or adjustable, and how is it determined? |
| Fees | Which costs are due at closing, and which are financed? |
| Available proceeds | What assumptions and existing balances affect this estimate? |
| Disbursement terms | When and how could funds be made available? |
Look at the full set of terms rather than treating the largest estimated proceeds as the best offer. If a lender’s numbers differ substantially from another estimate, ask for the specific assumptions behind that difference.
Ask who will handle your application and answer questions
A clear point of contact can make a complex process easier to follow. Ask who will collect documents, who will explain conditions, and how you can get an update when the file moves to appraisal or underwriting. Find out whether you will speak with the same person throughout or work with several members of a team. The answers give you a practical sense of how communication may work after you apply.
Prepare for required counseling and the application
Independent counseling is required for a HECM and gives you time to discuss the loan with someone separate from the lender. It is also a useful point to test whether the loan’s costs, obligations, and payout options fit your needs. Kingwood Mortgage Guy’s companion reverse-mortgage guide is a resource for preparing general questions, but it is not a substitute for HUD-approved counseling. Bring your own concerns, including anything you do not yet understand.
Schedule independent counseling with a HUD-approved counselor
Arrange counseling with a government-approved counselor before you proceed with the HECM application. The counselor can explain the loan’s requirements and give you an independent setting to ask questions. Ask what documents or information to bring, and take notes on any points you want to revisit with lenders. Use the meeting to discuss your own priorities rather than simply confirming a lender’s recommendation.
Gather identification, income, insurance, and mortgage documents
Preparing the basic paperwork early can help you respond when the lender requests information. Kingwood Mortgage Guy’s mortgage document checklist describes common records borrowers may need to assemble; confirm the exact list with your reverse mortgage lender, since requirements vary. Depending on your situation, organize items such as:
- Proof of age and identification.
- Social Security number and income documentation.
- Homeowner’s insurance information.
- A current mortgage statement and details of other liens.
Keeping the records together makes it easier to see what is ready and what still needs to be requested. Avoid sending sensitive documents through an unverified channel; ask the lender how to submit them securely.
Review title requirements and any existing liens
The lender will review title and check for issues that may affect the loan, including whether federal liens are present. Existing mortgages and other property liens matter because they may need to be paid from the proceeds. Ask for an explanation of any title concern and whether you need to provide additional records. If ownership details are complicated, consider getting appropriate legal advice before relying on a general explanation.
Ask how credit, income, or property issues could affect approval
If you have concerns about income, credit history, property condition, or other financial obligations, raise them early. The lender can tell you what it needs to review, but only a full assessment can clarify the effect on your application. Ask whether additional documentation or steps may be required and request the answer in writing when practical. This can help you avoid treating an early estimate as an approval.
Follow the appraisal and underwriting process
After application, the lender generally arranges an independent appraisal and reviews your paperwork. An appraisal helps establish the home’s value and whether it meets minimum property standards, while underwriting determines whether the loan is approved, approved with conditions, or denied. Timelines vary by lender and borrower, so ask what to expect and what could slow the process. Staying organized and answering requests promptly can make your part of the process more manageable.
Understand what the appraiser evaluates
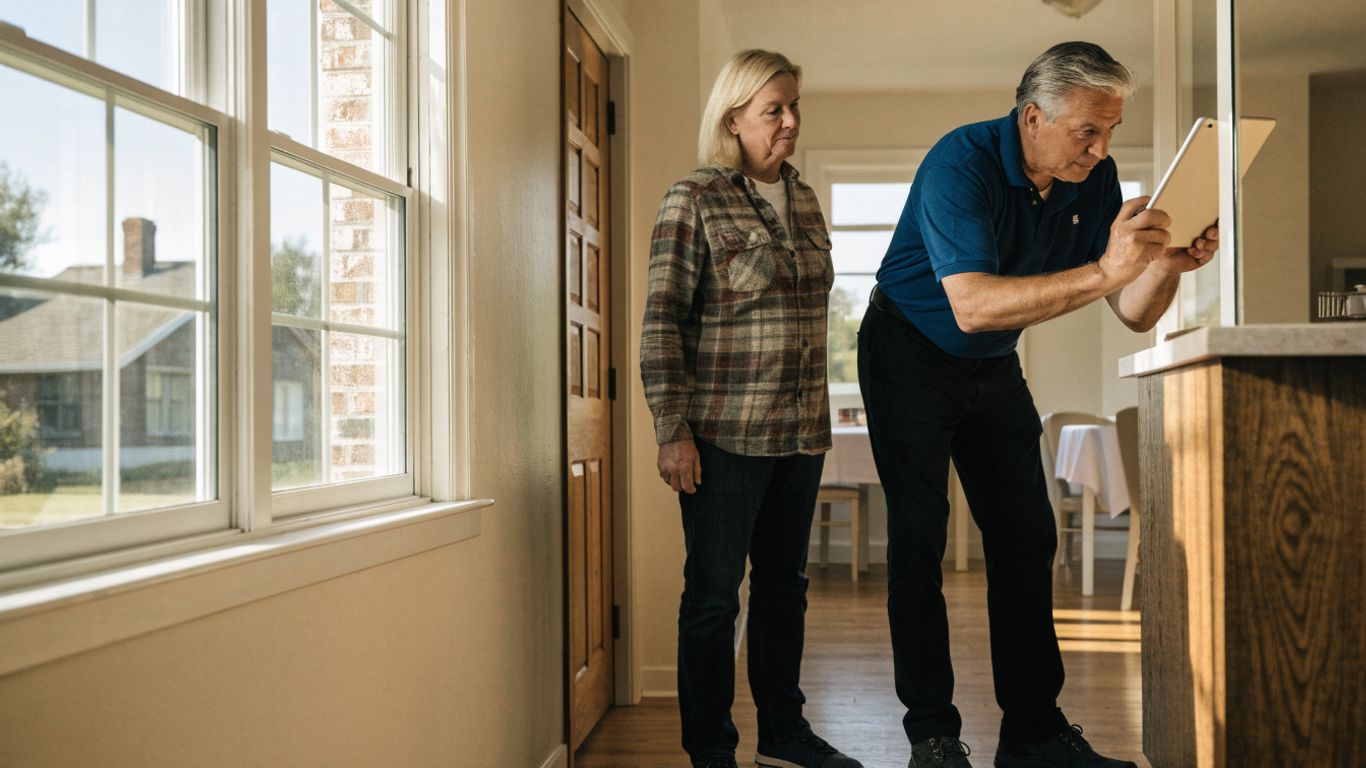
An independent, third-party appraiser visits the home on the lender’s behalf. The appraisal helps determine the home’s value and whether it meets applicable property standards for a reverse mortgage. Ask the lender what the visit involves and whether there are documents or access arrangements you should prepare. The appraisal is one input into the loan decision, not a guarantee of a particular loan amount.
Plan for repairs or property-condition requirements
If the appraisal identifies a condition that needs attention, ask the lender what work is required, when it must be completed, and how completion will be verified. Do not assume that every repair will be handled the same way; the answer depends on the finding and the loan requirements. Request a written explanation and discuss how the work could affect your budget or schedule. Clear instructions can help you avoid doing unnecessary work or overlooking a required step.
Respond to underwriting requests and loan conditions
An underwriter reviews the submitted information to decide whether the application is approved, approved with conditions, or denied for a particular reason. If the approval has conditions, you may need to provide more documents or complete other steps before closing. Read each request carefully, note its deadline, and ask the lender to explain anything unclear. Keeping copies of what you submit can help you track the file and follow up on outstanding items.
Confirm how lender-specific timelines may affect your plans
A closing date is not certain until outstanding requirements are satisfied. Ask the lender for its current estimate, which steps remain, and whether any appraisal, title, or document issue could change the timing. The lender’s estimate is not a promise: timelines vary by lender and borrower. If you are coordinating other financial decisions around the loan, leave room for delays rather than counting on funds by a particular date.
Choose how to receive and use the proceeds
Reverse mortgage proceeds may be available in different ways, depending on the loan terms and your needs. You may be able to consider a lump sum, a line of credit, monthly payments, or a combination. Think about how much you need now, whether you may need funds later, and how each structure fits your household budget. Ask the lender to explain the costs and conditions attached to each choice before selecting one.
Compare a lump sum, line of credit, monthly payments, or a combination
A lump sum provides funds at once, while monthly payments can provide a regular stream of proceeds under the chosen terms. A line of credit may let you draw funds as needed, and some arrangements allow a combination of options. Ask how the choice affects the amount available, the interest that accrues, and any restrictions on future access. Consider setting aside enough to meet near-term needs without overlooking future expenses.
Consider how a line of credit may grow and what conditions apply
Some HECM line-of-credit arrangements may grow over time under the loan’s terms, but the details depend on the specific agreement. Ask the lender to explain how any growth is calculated, when funds can be drawn, and what obligations you must meet to keep the account available. Do not base your decision on a projected future amount without understanding the assumptions behind it. Your counselor can help you add those terms to your overall comparison.
Understand how existing mortgages and liens are paid off
Current mortgages and eligible liens generally need to be addressed as part of closing, and loan proceeds may be used to pay them off. That means the amount left for you to receive can be less than the gross loan amount. Ask for a written breakdown that shows which balances and costs will be paid and what, if anything, remains for disbursement. Check those figures against your current statements and ask about any difference before signing.
Match the payout structure to your goals and budget
Your preferred payout method should reflect both today’s needs and the responsibilities you will continue to carry. Property taxes, insurance, and home maintenance remain part of your household budget, even if you are not making required monthly mortgage payments. Make a simple plan for how you would use the proceeds and what costs you will pay from other resources. A counselor or qualified financial professional can help you consider the broader implications for your circumstances.
Review closing documents and ongoing responsibilities
At closing, you meet with a notary to sign the reverse mortgage documents, often at home. Use that meeting to confirm that the final terms match what you discussed with the lender and that you understand what happens next. Do not feel rushed if something is unclear. Keep copies of the signed documents and the servicer’s contact information where you can find them.
Confirm the loan amount, fees, rate, and disbursement terms
Before signing, check that the documents state the loan amount, fees, interest rate, and how proceeds will be disbursed. Compare those terms with the most recent written explanation from the lender and ask about any difference. Make sure you understand which costs are paid from the proceeds and what conditions remain before funds can be distributed. You are entitled to have documents explained in plain language before you sign.
Use the rescission period to reconsider after closing
For many HECM transactions, you generally have a three-business-day right of rescission after closing, allowing you to cancel without penalty. Confirm the applicable deadline and cancellation instructions in your own documents rather than assuming how the period is calculated. If you reconsider, contact the lender or servicer promptly and follow the written process. Keep a copy of any notice you send.
Budget for property taxes, insurance, HOA dues, and upkeep
A reverse mortgage does not remove the need to meet ongoing responsibilities tied to the home. You must continue to maintain the property and stay current on property taxes and homeowner’s insurance; if the home is part of an association, budget for HOA dues as well. Build these costs into a realistic plan before closing. If you anticipate difficulty paying them, raise that concern with your counselor and lender while you are still evaluating the loan.
Know how occupancy and loan-servicing requirements apply
The home generally must remain your principal residence, and a permanent move can cause the loan to become due. Ask how temporary absences, extended care stays, and changes in household circumstances are treated under your documents. After closing, your loan servicer is the main contact for questions about the balance, draws, and obligations. Save its direct contact details and ask whom to call if your circumstances change.
Conclusion
Choosing a reverse mortgage lender in Kingwood takes careful comparison, independent counseling, and an honest look at your plans for the home. Review the written terms, ask how each stage may affect your timeline, and move forward only when you understand both the proceeds and the responsibilities that come with them.
Frequently Asked Questions
What does a reverse mortgage do?
A reverse mortgage lets an eligible homeowner access home equity without required monthly mortgage repayments. The balance grows and is generally repaid later, such as when the home is sold or the borrower moves out permanently.
Do you still own your home with a reverse mortgage?
Yes. The homeowner generally retains title and ownership, while remaining responsible for the loan’s terms and ongoing obligations such as property taxes, insurance, and upkeep.
How do you compare reverse mortgage lenders?
Request written estimates from more than one lender and compare rates, fees, payout terms, and service. Check credentials and complaint resources, and ask each lender to explain assumptions behind its figures.
Is counseling required for a HECM?
Yes. HECM borrowers must meet with a government-approved counselor independently of the lender so they can discuss the loan’s requirements and ask questions before making a decision.
What happens to an existing mortgage?
Existing mortgages and liens may need to be paid from the reverse mortgage proceeds at closing. The amount available to you after those payments can therefore be lower than the total loan amount.
Can you choose how to receive reverse mortgage proceeds?
Depending on the loan terms, proceeds may be available as a lump sum, a line of credit, monthly payments, or a combination. Ask the lender to explain the conditions and costs for each option.
What responsibilities continue after closing?
You generally need to maintain the home, keep property taxes and insurance current, and comply with occupancy and loan-servicing requirements. Review your documents and contact the servicer if you have questions or your circumstances change.